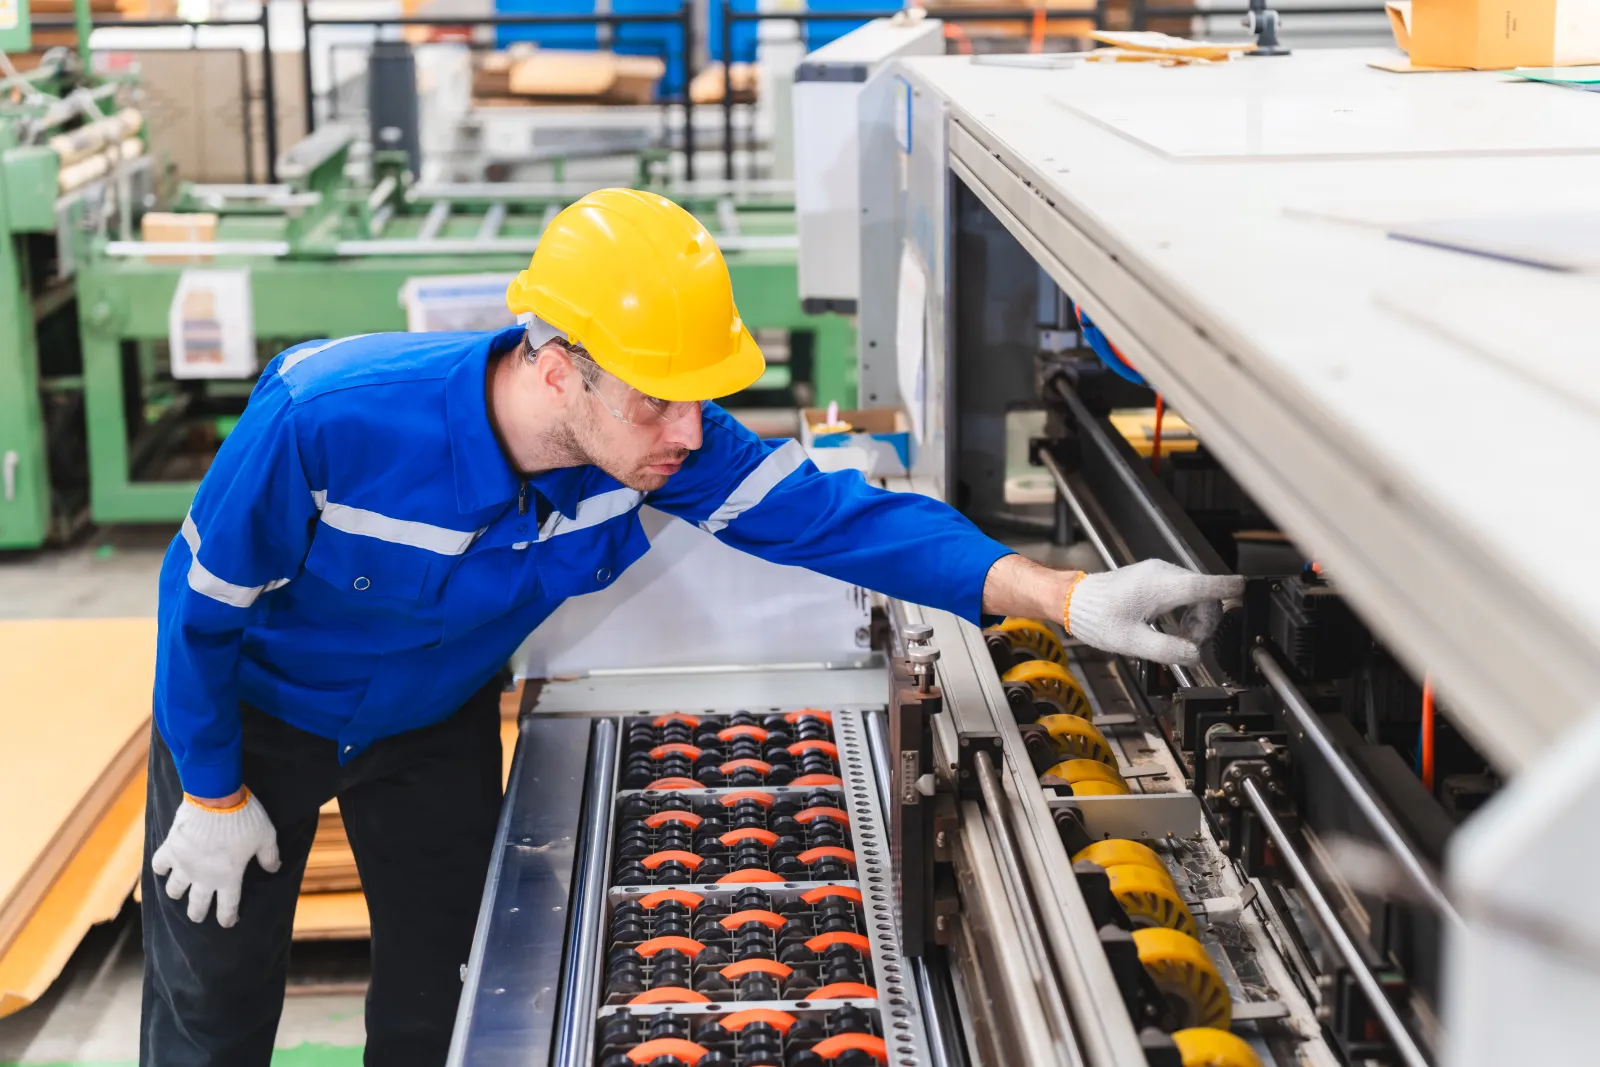
A plant manager in Gebze opens the BOM that came with the group template. It lists 1.00 unit of resin per finished part. The line actually consumes more, because every changeover purges material, and the local supplier ships the resin in a grade the template never mentioned. Purchasing orders against the template, production issues against reality, and the gap shows up months later as an unexplained variance in the cost accounts.
This guide explains how to structure a bill of materials (BOM) in an ERP so that it reflects what the plant really does, and how to keep it accurate once people start changing it.
Note: Cost accounting treatment and statutory reporting depend on your situation. Confirm with your financial advisor.
What is a multi-level BOM?
A multi-level BOM describes a finished product as a tree. The top is the sellable item. Below it sit sub-assemblies, and below those, raw materials and packaging. Each level has its own quantity, unit and, where relevant, its own production step.
A flat BOM, one list of raw materials per finished item, hides the sub-assemblies. That is acceptable for a simple mix-and-pack operation. It stops working the moment a sub-assembly is also sold, stocked or produced on a different line.
When should a sub-assembly be its own item?
Give a sub-assembly its own item code when any of the following is true.
- It is produced in a separate work order or on a separate line.
- It is held in stock between steps.
- It is purchased in some periods and made in others.
- It appears in more than one finished product.
If none applies, keep it as a transient step. Too many stocked intermediates create counting work and cost allocation questions with no planning benefit.
How should yield and scrap be recorded?
Record the quantity a good unit needs, not the theoretical quantity on the drawing. There are two ways to do it, and the choice should be explicit.
| Approach | How it works | Best for |
|---|---|---|
| Scrap factor in the BOM | Component quantity is inflated by an expected loss percentage | Stable, predictable losses such as cutting and trimming |
| Actual consumption reported at the work order | The BOM holds the standard quantity and the variance is reported separately | Processes where loss varies by batch, such as mixing or casting |
Mixing both on the same component double-counts the loss. Pick one per component and document it.
Review the figures against actual issues from the work orders at least once a quarter. A scrap factor nobody revisits becomes a hidden allowance.
How are BOM revisions controlled?
Product changes are normal. Uncontrolled changes are the problem. A revision process needs four rules.
- Effective dates. Each revision has a start date. Work orders released before that date keep the old revision.
- One approver per change. Engineering proposes, production confirms the line can run it, and cost accounting sees the effect on standard cost. Nobody edits a live BOM directly.
- Reason recorded. Supplier change, design change, cost reduction or quality fix. This is the first thing an auditor or a group controller asks.
- Old revisions stay readable. Returns, warranty claims and traceability questions refer to products built months ago.
How should substitute materials be handled?
Turkish plants substitute components regularly, because of supply disruption, import lead times or price. The risk is doing it informally on the shop floor.
Define approved substitutes inside the BOM, with a priority order and, where relevant, a conversion ratio. The work order then offers the alternative when the primary is short, and the substitution is recorded against the batch. Without that record, a quality complaint cannot be traced to the material actually used.
For products with variants such as size or colour, keep one parent structure and let the variant change only the components that differ. Copying a full BOM per variant multiplies maintenance work, and the copies drift apart.
How does the BOM drive planning and cost?
Once the BOM is reliable, three processes depend on it.
- Material requirements planning. Demand for a finished item explodes through the levels into requirements for sub-assemblies and raw materials, netted against stock and open orders.
- Standard cost. Material cost rolls up from the lowest level. Labour and overhead are added at each production step.
- Actual cost. Work order issues and receipts are compared with the BOM to produce material usage variances.
An inaccurate BOM corrupts all three at once. This is why BOM quality is a better first investment than any reporting tool.
How does Birasyo handle this?
Birasyo's Manufacturing module supports multi-level bills of materials and variant management, together with work orders and material planning. Shop-floor data feeds the work order, so consumption can be compared with the BOM instead of with a spreadsheet. If you want to test your own product structures, including one with sub-assemblies and substitutes, request a demo.
Questions to answer before you load BOMs
- Which sub-assemblies are stocked, sold or made on separate lines?
- For each component, is loss handled by a scrap factor or by actual reporting?
- Who approves a BOM change, and is the effective date recorded?
- Which substitute materials are approved today, and who authorised them?
- Are the BOMs in use the same as the group template, or did the plant adapt them?
Summary
- A multi-level BOM models sub-assemblies as separate levels. Give a sub-assembly its own item code only when it is stocked, sold, shared or made separately.
- Record loss through a scrap factor or through actual consumption, never both on the same component.
- Control revisions with effective dates, a single approval path, a recorded reason and readable history.
- Define approved substitutes in the BOM so the batch record shows what was actually used.
- A reliable BOM underpins material planning, standard cost and variance analysis together.
Sources
This article describes process design and contains no statutory figures. Cost accounting and reporting treatment under Turkish regulations should be confirmed with your financial advisor.
Share this post on LinkedIn
The title, summary and hashtags are copied to your clipboard and the sharing window opens. Paste (Cmd/Ctrl+V) and post.
