In late 2023 Türkiye's Public Oversight, Accounting and Auditing Standards Authority (KGK) mandated Türkiye Sustainability Reporting Standards (TSRS) S1 and S2 for in-scope entities, for accounting periods beginning on or after 1 January 2024. Businesses outside the scope are affected through their customers and banks.
TSRS S1 and S2 Explained
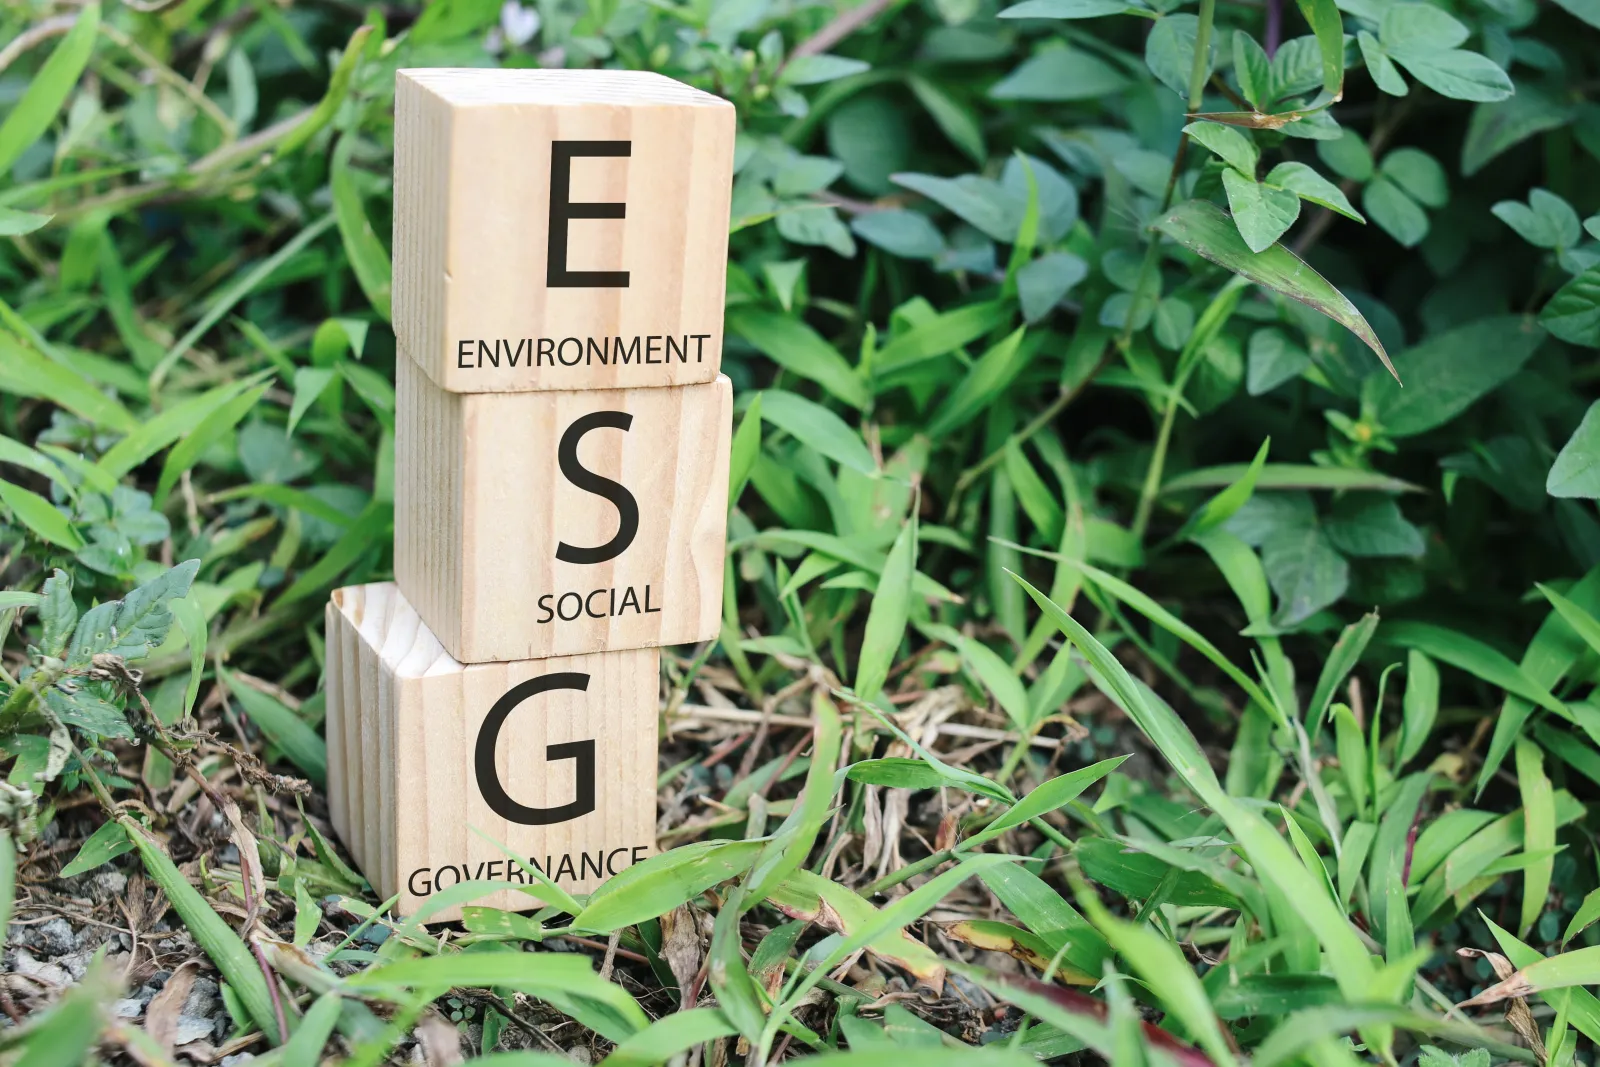
- TSRS S1, General Sustainability Disclosures: covers all sustainability risks and opportunities (environmental, social, governance)
- TSRS S2, Climate-Related Disclosures: Scope 1, 2, 3 emissions; climate transition plan; physical-risk assessment
Both align with IFRS S1/S2, so your disclosures are readable to international investors and lenders.
Who Must Report?
Who is in scope?
Under KGK's scope decision, TSRS is mandatory for accounting periods beginning on or after 1 January 2024. The scope is not every company: it covers the entity types listed in the decision, such as companies subject to capital-markets regulation (including those whose shares are listed), institutions subject to banking regulation, and insurance and pension companies.
Among those entities, the ones that exceed at least two of the following three thresholds in two consecutive reporting periods must report. KGK raised the thresholds for accounting periods beginning on or after 1 January 2025 (decision published in the Official Gazette of 16 January 2026, No. 33139):
- Total assets of TL 1 billion
- Annual net sales of TL 2 billion
- 500 employees
For accounting periods that began in 2024 the thresholds were TL 500 million, TL 1 billion and 250 employees.
Banks are in scope regardless of these thresholds.
The scope can change
KGK updates the scope through board decisions, so confirm the current decision on KGK's website for each reporting year.
If you are out of scope
Banks may request sustainability data for credit underwriting, and in-scope customers may request it from their suppliers, so you can be affected commercially even without a legal mandate.
Why TSRS Is Hard the First Time
Businesses in Türkiye typically face three obstacles:
- No retrospective data. Reports demand 12-24 months of emissions, energy and water data. Reconstructing it from paper and email takes months.
- Methodology gap. Scope 1/2/3 distinction, factor selection and boundary definition are technical subjects.
- Verification cost. TSRS requires assurance; messy data doubles audit hours and fees.
How Birasyo's Sustainability Module Helps
The module was built to address all three in one place:
- Automatic data pipeline: electricity invoices, fuel purchases and fleet telematics already live in the accounting module. Sustainability pulls and converts them to emissions
- GHG Protocol + ISO 14064-1 compliant calculations with traceable sources line-by-line
- Ready-made TSRS S1 and S2 templates exported as PDF/Excel in the format your auditor expects
- Target tracking aligned with SBTi net-zero paths, reported quarterly
What You Should Do Now
If you are in scope: stand up measurement immediately. When the accounting period closes, data must already be complete.
If you are near the thresholds: you come into scope if you are one of the entity types listed in the decision and you exceed at least two of the three thresholds in two consecutive periods. Confirm your entity type with your independent auditor, and start collecting Scope 1 and 2 data now so that preparation is not rushed.
If your customers are large BIST or EU companies: they will survey you for their own Scope 3 disclosures. Be able to answer quickly.
Request a TSRS readiness review via demo; we will assess together whether you are in scope and draw up a preparation plan.
Share this post on LinkedIn
The title, summary and hashtags are copied to your clipboard and the sharing window opens. Paste (Cmd/Ctrl+V) and post.